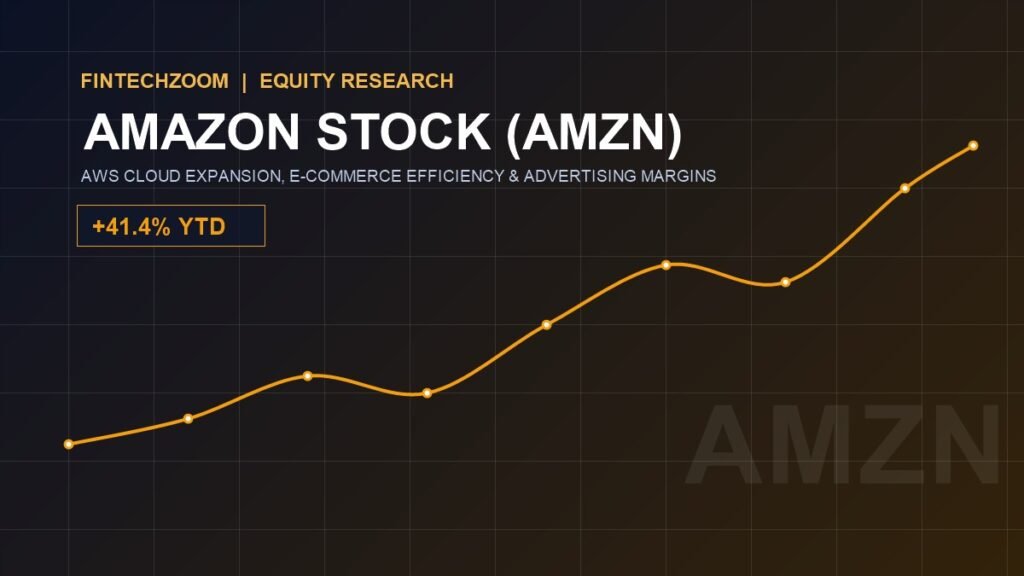
Quick Summary: FintechZoom Amazon stock analysis deconstructs real-time AMZN market pricing, the re-acceleration of Amazon Web Services (AWS), operational margin expansion across North American retail logistics, and high-margin digital advertising momentum. As CEO Andy Jassy optimizes regional fulfillment networks, Amazon is generating historic levels of free cash flow.
Amazon.com Inc. (NASDAQ: AMZN) has evolved from an online bookstore into the world’s most formidable commercial ecosystem. Today, Amazon operates as a multi-pillar conglomerate spanning global e-commerce, cloud computing infrastructure (AWS), third-party logistics fulfillment, digital advertising, and entertainment streaming. For traders tracking tech equities on FintechZoom.io stocks terminal, AMZN represents the ultimate intersection of consumer demand and enterprise cloud technology.
Following post-pandemic capital expenditure recalibration, Amazon has entered an era focused on operating leverage and cash flow optimization. On FinStechZoom, our institutional market desk breaks down the structural catalysts driving Amazon’s next leg of growth alongside peers like FintechZoom Microsoft stock and FintechZoom Google stock.
Fact-Checked & Verified
•
Reviewed by FintechZoom Financial Research Desk
•
Primary Sources: SEC EDGAR, NASDAQ, Bloomberg Terminals
•
Editorial Policy
Live AMZN Trading Action & Operating Margin Inflection
Historically, Amazon was known for reinvesting every dollar of gross profit back into fulfillment warehouses, data centers, and new initiatives, suppressing reported net income. However, over the past several quarters, Amazon’s operating margin has expanded into double-digit territory, surprising Wall Street and driving massive institutional accumulation across broad indexes like the FintechZoom S&P 500 index.
This margin expansion is not an accident; it is the direct result of structural improvements across fulfillment regionalization, advertising penetration, and AWS enterprise renewals. As institutional investors recognize that Amazon has shifted from a low-margin retail distributor to a high-margin services platform, AMZN’s multiple expansion thesis continues to gain traction.
AWS Re-Acceleration: The Cloud Crown Jewel
Amazon Web Services (AWS) remains the world’s largest public cloud infrastructure provider by market share. After experiencing a brief period of customer enterprise cost-optimization following the post-pandemic cloud boom, AWS has re-accelerated to strong double-digit annual growth rates.
Key Drivers of AWS AI Leadership
- Custom Silicon (Trainium & Inferentia): While AWS offers extensive clusters of Nvidia chips (as explored in our FintechZoom NVDA stock report), Amazon has invested heavily in its own proprietary AI chips—Trainium2 and Inferentia2. These custom accelerators offer clients up to 40% to 50% better price-performance for training and running generative AI models, driving significant margin preservation for AWS.
- Amazon Bedrock: Rather than forcing enterprises into a single proprietary model, Amazon Bedrock provides an enterprise-secure marketplace where developers can choose from Anthropic’s Claude 3.5 Sonnet, Meta’s Llama 3, Mistral, and Amazon’s own Titan models via a unified API.
- Deep Corporate Infrastructure Backlog: AWS boasts a multi-billion dollar contracted backlog with enterprise clients signing multi-year cloud commitments, providing outstanding revenue predictability.
The Retail Miracle: Fulfillment Regionalization & Robotics
The single greatest operational turnaround under Andy Jassy’s leadership has been the complete overhaul of Amazon’s U.S. logistics network. Previously operating as a centralized national fulfillment system, Amazon reorganized its infrastructure into eight self-contained regional hubs.
Financial Impact of Regionalization
- Shorter Transit Distances: By stocking inventory closer to the end consumer, packages travel fewer miles and require fewer touches, drastically reducing line-haul transportation costs.
- Faster Delivery Times: Same-day and next-day delivery speeds have reached all-time records, increasing Prime customer shopping frequency and average order value (AOV).
- Warehouse Robotics Deployment: The rollout of Sequoia and Proteus autonomous mobile robots in fulfillment centers has compressed fulfillment costs per unit by double digits, structurally lifting retail segment operating margins.
Digital Advertising: Amazon’s Secret High-Margin Engine
While retail and cloud dominate headlines, Amazon’s digital advertising services division has quietly grown into a $50+ billion annual revenue powerhouse, establishing itself as the undisputed third pillar of the global digital ad duopoly alongside Alphabet and Meta.
Unlike search engines or social media feeds where user intent is speculative, advertising on Amazon occurs directly at the digital point of sale. When a consumer searches for a product on Amazon, their purchase intent is immediate. This gives Amazon’s Sponsored Products and Sponsored Brands advertising tools industry-leading Return on Ad Spend (ROAS).
Furthermore, the introduction of commercial advertising on Prime Video has unlocked tens of billions in premium Connected TV (CTV) brand advertising budgets, boasting estimated operating margins well north of 60%.
Financial Metrics & Valuation Benchmark
Review Amazon’s core valuation and operational metrics against technology and retail sector benchmarks:
| Financial Indicator | AMZN Performance (2026) | Sector Median | Strategic Evaluation |
|---|---|---|---|
| Market Capitalization | $2.0T – $2.3T | $150B (Consumer / Tech) | Global commercial hegemony |
| AWS Operating Margin | 33.5% – 37.0% | 20.0% | Massive enterprise cloud profitability |
| Forward P/E Ratio | 28.0x – 32.5x | 24.0x | Compelling given rapid 25%+ EPS growth |
| Advertising Services Revenue | $54B+ Annual Run-Rate | N/A | High-margin recurring cash engine |
| Free Cash Flow TTM | $60B+ | $8B | Historic inflection toward shareholder value |
Wall Street Outlook & 2026 Price Targets
Wall Street consensus on Amazon is overwhelmingly bullish. Out of over 50 covering brokerage firms, over 95% rate AMZN a “Strong Buy.” Consensus 12-month target prices range between $230 and $265 per share, reflecting an expectation of sustained margin expansion and free cash flow generation.
Key Investment Catalysts to Watch
- Sustained Operating Leverage: Each incremental percentage point of operating margin improvement in North American retail adds billions directly to pre-tax earnings.
- Project Kuiper Satellite Broadband: Amazon’s low-Earth-orbit satellite constellation represents a massive optionality play to deliver broadband internet to underserved enterprise, consumer, and maritime markets worldwide.
- Healthcare Expansion: Amazon Pharmacy and One Medical integrations continue to build momentum, providing another multi-hundred-billion dollar addressable market.
Conclusion: The Ultimate Compounder
Amazon has successfully engineered a structural transition from a hyper-growth, zero-margin e-commerce retailer into a diversified global technology and services powerhouse generating tens of billions in annual free cash flow. For investors looking across the FintechZoom global markets sector, AMZN offers an exceptional combination of defensive market share moats and aggressive technological optionality.
Important Financial & Regulatory Risk Disclaimer
FintechZoom is an independent financial news, educational portal, and market research publisher. All information, technical benchmarks, stock forecasts, and equity data provided in this publication are strictly for general educational and informational purposes only. Nothing herein constitutes personalized investment, financial, legal, accounting, or tax advice, nor should it be interpreted as a solicitation or recommendation to buy, sell, or hold any security.
Trading in securities, equities, exchange-traded funds (ETFs), and derivatives involves substantial capital risk, including the possible total loss of principal. Past performance is no guarantee of future returns. Before executing any trades, readers must perform their own due diligence and consult a qualified, licensed financial professional. Read our complete legal disclosures in our Terms of Use.
