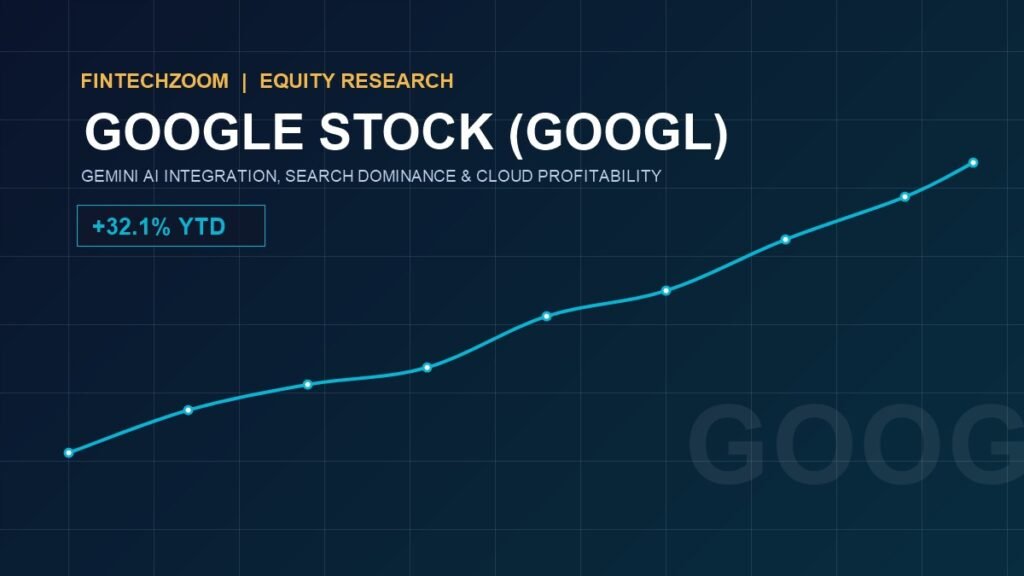
Quick Summary: FintechZoom Google stock analysis covers live Alphabet Inc. (NASDAQ: GOOGL / GOOG) valuation, Gemini multimodal AI integration across search, expanding Google Cloud operating margins, and YouTube monetization trends. With the lowest forward P/E multiple among the “Magnificent Seven” tech titans, Alphabet represents one of the most compelling risk-adjusted value propositions in large-cap equities.
Alphabet Inc. (NASDAQ: GOOGL / GOOG) occupies an extraordinary position in the modern global economy. Controlling over 90% of global internet search market share through Google Search, the world’s most widely watched video streaming platform in YouTube, the world’s dominant mobile operating system in Android, and a rapidly expanding enterprise cloud infrastructure in Google Cloud Platform (GCP), Alphabet touches billions of digital interactions every day.
Despite early market skepticism regarding the disruption of traditional search by conversational AI, Alphabet has executed a swift and aggressive counteroffensive with its proprietary Gemini foundation models. On FinStechZoom, our equity research tracks how Alphabet is preserving its high-margin advertising moat while scaling enterprise cloud profitability alongside peers like FintechZoom Apple stock and FintechZoom Microsoft stock.
Fact-Checked & Verified
•
Reviewed by FintechZoom Financial Research Desk
•
Primary Sources: SEC EDGAR, NASDAQ, Bloomberg Terminals
•
Editorial Policy
Live GOOGL Market Valuation: The Value Play of Big Tech
Throughout market cycles on the FintechZoom.io Nasdaq tech board, Alphabet has consistently traded at a noticeable valuation discount relative to Apple, Microsoft, and Nvidia. While competitors often command forward price-to-earnings multiples exceeding 30x, GOOGL frequently trades between 21x and 24x forward earnings.
This valuation gap has created what many institutional asset managers describe as the premier “growth-at-a-reasonable-price” (GARP) opportunity in the tech sector. Supported by a pristine cash position exceeding $100 billion, initiation of a quarterly cash dividend, and aggressive share repurchase programs, Alphabet’s capital return framework is among the strongest in the S&P 500.
The Gemini AI Transition: Defending the Search Franchise
The primary concern cited by Wall Street bears has been whether generative AI chatbots would cannibalize search queries and degrade Google’s ad-click business model. In 2026, the empirical data tells a vastly different story:
- AI Overviews Scaling: Google has successfully rolled out AI Overviews to over one billion users across multiple languages. Rather than reducing queries, multi-turn AI responses have increased total search engagement, particularly for complex, multi-layered queries.
- Ad Monetization Within AI Answers: Advertisers have seamlessly integrated into AI Overviews, with commercial links displaying relevant products, booking options, and sponsored recommendations directly beneath AI summaries, maintaining strong Cost-Per-Click (CPC) dynamics.
- Full-Stack Silicon Advantage (TPUs): Unlike competitors who rely solely on third-party GPUs, Google has designed and deployed its custom Tensor Processing Units (TPUs) for over a decade. By training and running Gemini on TPU v5e and v5p hardware, Google operates with significantly lower compute inference costs than startups relying entirely on commodity merchant silicon.
Google Cloud Platform (GCP): Accelerating Operating Profitability
One of the most consequential developments in Alphabet’s financial profile is the maturation of Google Cloud Platform (GCP). After spending years in heavy investment phases with negative operating margins, GCP has achieved significant scale, posting expanding double-digit operating margins.
GCP’s Core Growth Catalysts
- The Premier AI Startup Destination: Over 70% of leading generative AI startups and unicorn ventures run on Google Cloud, drawn by GCP’s advanced TPU infrastructure, Vertex AI development platform, and open-source model support.
- Enterprise Security (Mandiant): Following the acquisition of Mandiant, Google Cloud has become a preferred destination for cybersecurity operations, helping sovereign governments and Fortune 500 banks detect advanced persistent threats (APTs).
- BigQuery Data Analytics: Enterprise customers continue to migrate multi-petabyte analytics workloads into BigQuery, providing high-margin, sticky cloud storage and compute revenue.
Key Financial Benchmarks & Segment Performance
Here is how Alphabet’s operating fundamentals compare across key financial categories:
| Financial Benchmark | GOOGL Benchmark (2026) | Big Tech Median | Strategic Evaluation |
|---|---|---|---|
| Market Capitalization | $2.1T – $2.4T | $2.8T | Top 5 global equity ranking |
| Forward P/E Ratio | 20.5x – 23.5x | 30.0x | Significant multiple discount to peers |
| Google Cloud Operating Margin | 9.5% – 12.0% | N/A | Rapidly expanding from break-even to profit engine |
| YouTube Total Run-Rate | $40B+ (Ads + Subs) | N/A | Dominant global video streaming platform |
| Free Cash Flow (Annual) | $70B+ | $18B | Unmatched cash compounding capability |
YouTube: The Global Streaming Powerhouse
YouTube represents an underappreciated gem within Alphabet’s empire. While legacy broadcast television experiences ongoing cord-cutting, YouTube commands the largest share of total TV streaming watch time in the United States, outpacing Netflix, Disney+, and Amazon Prime Video according to Nielsen ratings.
Furthermore, YouTube has successfully diversified away from purely cyclical ad spending through YouTube TV (the fastest-growing pay-TV distribution service in the U.S. featuring NFL Sunday Ticket) and YouTube Premium subscriptions, which recently surpassed 100 million global subscribers. This creates sticky, recurring subscription cash flows that balance advertising seasonality.
Regulatory Headwinds & The Antitrust Landscape
The primary reason for Alphabet’s valuation discount is the overhang from ongoing Department of Justice (DOJ) and European Commission antitrust litigations concerning search distribution agreements (such as revenue-sharing deals with Apple) and digital ad-tech stack operations.
However, historical precedents (such as the Microsoft antitrust case in the early 2000s) suggest that remedy phases take years of appellate review to resolve. Even in worst-case scenarios involving operational unbundling or structural divestitures, market strategists note that a sum-of-the-parts (SOTP) valuation of Alphabet—evaluating Google Search, YouTube, Google Cloud, Android, and Waymo as standalone entities—often yields a higher total enterprise valuation than Alphabet’s current consolidated market cap.
Strategic Verdict: A Compelling Risk-Reward Profile
Alphabet offers one of the most attractive risk-reward asymmetric bets in the large-cap technology universe. With its proprietary TPU silicon, massive distribution footprint across Android and Chrome, expanding Cloud profitability, and leadership in autonomous driving via Waymo, Google is exceptionally positioned to compound shareholder value throughout the remainder of the decade.
Important Financial & Regulatory Risk Disclaimer
FintechZoom is an independent financial news, educational portal, and market research publisher. All information, technical benchmarks, stock forecasts, and equity data provided in this publication are strictly for general educational and informational purposes only. Nothing herein constitutes personalized investment, financial, legal, accounting, or tax advice, nor should it be interpreted as a solicitation or recommendation to buy, sell, or hold any security.
Trading in securities, equities, exchange-traded funds (ETFs), and derivatives involves substantial capital risk, including the possible total loss of principal. Past performance is no guarantee of future returns. Before executing any trades, readers must perform their own due diligence and consult a qualified, licensed financial professional. Read our complete legal disclosures in our Terms of Use.
